

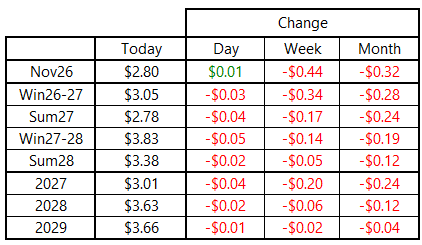
Natural gas futures were little changed on Thursday following a sharp selloff over the past several sessions. The November 2026 NYMEX contract edged 1 cent higher to finish at $2.80 per MMBtu, although prices continued to soften further out the forward curve. The Winter 2026-27 strip declined 3 cents to $3.05 per MMBtu, while Summer 2027 fell 4 cents to $2.78. Despite Thursday’s relatively quiet session, the November contract is down 44 cents over the past week, with the full Winter 2026-27 strip giving up 34 cents over the same period.
The EIA reported a 77-Bcf storage injection this morning, marking the tenth consecutive week in which the build fell short of the five-year average. Over that stretch, the inventory surplus has narrowed from 198 Bcf to just 35 Bcf, while stocks are now 152 Bcf below year-ago levels.
Despite the continued tightening of the storage balance, weather remains the dominant influence on near-term market sentiment. Forecasts calling for widespread mild temperatures through the remainder of October and into early November are limiting expectations for heating demand and weighing on prices. With inventories still relatively comfortable heading into winter, the market appears willing to look past the recent string of below-average injections until colder weather provides a more meaningful catalyst for demand.
An archive of Daily Natural Gas Market Notes can be found here.
The 77-Bcf injection being the tenth straight build below the five-year average, with the surplus narrowing from 198 to 35 Bcf, is notable. It makes the mild weather forecasts the main thing holding prices down for now.